A 10 percent down construction loan is attainable in Arizona, most commonly through conventional one-time-close programs, and often for less cash than that if you already own your lot. Lenders will also flex the numbers lower through FHA and VA one-time-close options, though each comes with its own strings attached. Here’s what to line up before you talk to a lender:
- Check your lot status. Owned land with equity can offset part or all of your required down payment.
- Confirm program eligibility. FHA needs 3.5% down; VA can go to 0% for qualifying veterans.
- Get your builder ready. Lenders want to see an Arizona Registrar of Contractors (ROC) license and current insurance before they’ll fund a draw.
Key Takeaways
A 10 percent down construction loan in Arizona is realistic through conventional one-time-close programs, and lot equity or FHA/VA eligibility can lower that number further.
| Point | Details |
|---|---|
| Conventional 10% programs exist | Some Arizona credit unions offer 10% down on loan amounts up to $1,500,000 with one-time-close terms. |
| FHA and VA change the math | FHA one-time-close allows 3.5% down; VA one-time-close allows 0% for eligible veterans. |
| Lot equity counts | An appraised, owned lot’s equity can cover part or all of your required down payment. |
| Reserves matter as much as down payment | Budget an additional 5% to 10% in contingency reserves on top of your down payment. |
| Better Quality Builders coordinates financing | Better Quality Builders pairs AirLight steel panel construction with combined land and construction financing support for Arizona buyers. |
Table of Contents
- What Are the Arizona Construction Loan Options for 10% Down?
- How Do Lenders Calculate a 10% Down Construction Loan?
- What Do Lenders Require to Approve a Low Down Payment Construction Loan?
- Can Owning Your Lot Reduce Your Down Payment?
- What Does a 10% Down Construction Loan Look Like in Dollars?
- Why Better Quality Builders Is a Direct Path to 10% Down Financing in Arizona
- What Arizona Homebuyers Get Wrong About 10% Down Financing
- Frequently Asked Questions About 10% Down Construction Loans in Arizona
- Sources
What Are the Arizona Construction Loan Options for 10% Down?
Conventional construction loans are the most direct path to 10% down in Arizona. Some credit unions advertise down payments as low as 10% on loan amounts up to $1,500,000, paired with one-time-close structures and 12 to 18 month build windows. Not every conventional product lands there, though. The same lenders that offer 10% programs sometimes require 25% down on other construction loan types, depending on loan size, property type, and your credit profile.
FHA and VA one-time-close loans sit at the edges of that range:
- FHA one-time-close: as low as 3.5% down, subject to county loan limits and mortgage insurance premiums. Read the mechanics in our FHA construction loan guide.
- VA one-time-close: 0% down for eligible veterans, but the builder must be VA-approved and occupancy rules apply.
- Portfolio and jumbo lenders: more flexible underwriting for stronger borrower profiles, though rarely a shortcut to a lower down payment.
If you’re aiming for 10 percent down mortgage Arizona terms specifically, conventional programs are usually where you’ll find it, especially once lot equity enters the equation.
How Do Lenders Calculate a 10% Down Construction Loan?
Down payment math on a construction loan isn’t as simple as multiplying a sale price by 10%. Lenders base the calculation on total project cost, land plus build, though they often exclude certain soft costs from that basis, so ask your loan officer exactly what’s included before you run your own numbers.
- Total project cost is set first. Land value (or purchase price) plus the fixed construction contract amount forms the loan basis.
- Draws release in stages. You don’t get the full loan upfront; funds disburse as framing, roughing, and finishing milestones are completed and inspected.
- Interest-only payments apply to drawn funds. You’re not paying interest on the whole loan the day you close, only on what’s actually been disbursed.
- One-time-close locks in permanent financing upfront, which avoids a second qualification round and a second set of closing costs once the home is finished.
- Two-time-close means a separate application later, with new rate risk and new underwriting when you convert to a permanent mortgage.
- Underwriters typically plan for 12 to 18 months of construction, and your loan terms will reflect that build window.
Our guide on financing a new home build walks through the close-to-permanent transition in more detail.
What Do Lenders Require to Approve a Low Down Payment Construction Loan?
Getting approved for a low down payment construction loan comes down to four things: your credit, your debt load, your builder, and your paperwork.
- Credit score: conventional programs price best around 680 to 720+, while FHA typically floors around 620.
- Debt-to-income ratio: lenders want room in your monthly obligations, plus proof you can cover contingency reserves of roughly 5% to 10% of the construction budget.
- Builder approval: your lender will verify AZ ROC licensing, insurance, and builder track record before releasing any draw.
- Documentation: a fixed-price build contract, plans and specifications, an itemized budget, lot deed or appraisal, and standard personal financial records.
Lenders scrutinize the builder almost as closely as they scrutinize you, since a construction loan is riskier collateral than a finished home. A vague, unlicensed contractor can sink an otherwise strong application.
Can Owning Your Lot Reduce Your Down Payment?
Yes. If you already own your lot, its appraised equity can count toward your down payment, sometimes covering the entire requirement.
Say your lot appraises for $80,000 more than what you owe on it, and your project needs $75,000 down. That equity alone could clear the requirement with no cash due at closing. A smaller equity cushion still chips away at what you’d otherwise need to bring.
Lenders will ask for comprehensive support across your project, and local options in Landscaping Service Areas in Southern Arizona can help with post-build site preparation.
- A current appraisal of the lot
- A title report
- Payoff statements for any existing liens on the land
What Does a 10% Down Construction Loan Look Like in Dollars?
Numbers make this real. Here are two simplified scenarios, using round figures and excluding lender fees and soft costs for clarity.
- Mid-size custom build, $450,000 total project cost (land + build). A 10% down payment is $45,000. A 7.5% contingency reserve adds roughly $33,750 in required reserves. If $200,000 is drawn at a given point during construction, interest-only payments apply to that drawn amount only, not the full loan.
- Larger custom build, $850,000 total project cost. Ten percent down comes to $85,000, with a 10% contingency reserve near $85,000 as well. Draws again determine your interest-only payment at any given stage, not the total loan amount.
FHA changes the first scenario’s out-of-pocket cash to roughly $15,750 at 3.5% down, subject to county limits. VA-eligible veterans could bring $0 down on either scenario, assuming a VA-approved builder and occupancy compliance. Our breakdown of what a custom home costs to build in Arizona covers how contingency assumptions shift with project size.
Why Better Quality Builders Is a Direct Path to 10% Down Financing in Arizona
That construction approach pairs directly with the financing conversation. Better Quality Builders publishes detailed guidance on FHA construction loans and coordinates combined land and construction financing, which matters when a lender wants land value and build cost calculated together for your 10% down basis.
Before you reach out, get these ready:
- Proof of lot ownership or purchase agreement
- Your target floor plan or customization notes
- A rough budget range for the build
Pro Tip: Pull your lot’s most recent appraisal or tax assessment before your first call. It speeds up how quickly a lender can tell you what your equity actually covers.
What Arizona Homebuyers Get Wrong About 10% Down Financing
It isn’t. It’s a range that shifts based on loan size, program type, and whether your lot equity gets applied before or after the down payment calculation. A buyer with a paid-off half-acre lot in Maricopa County might walk into closing with less cash required than a buyer financing the same house from scratch, even at the same advertised rate.
Conventional advice tends to fixate on the down payment percentage and undersell contingency reserves.
If there’s one place to focus first, it’s the builder relationship, not the loan officer. An AZ ROC licensed builder with a clean, itemized fixed-price contract makes underwriting faster and your down payment target easier to hit, because the lender’s risk assessment leans heavily on who’s actually swinging the hammer.
Building With AirLight Panels and 10% Down Financing
Better Quality Builders is the direct route to a steel panel custom home in Arizona without navigating land and construction financing as two separate headaches.
Because Better Quality Builders coordinates combined land and construction financing, your lender sees a builder who’s already vetted, licensed, and set up to document draws cleanly, which is exactly what underwriters look for when approving a low down payment construction loan. Instead of shopping a floor plan, then a lender, then a lot, you work through one process built around AirLight steel panel homes designed for Arizona’s climate and building codes. Browse available custom home plans and reach out to start pairing your financing timeline with a real build schedule.
Frequently Asked Questions About 10% Down Construction Loans in Arizona
Yes, through conventional one-time-close construction programs offered by several Arizona lenders, though loan size and credit score affect whether you qualify at that level.
Does FHA or VA financing lower the down payment even further?
How does owning my lot affect my down payment? An appraised, owned lot’s equity typically counts toward your required down payment, which can significantly reduce or eliminate out-of-pocket cash at closing.
What credit score do I need for a 10 percent down mortgage Arizona construction loan? Conventional programs generally price best at 680 to 720 or higher, while FHA-backed construction loans typically require a minimum around 620.
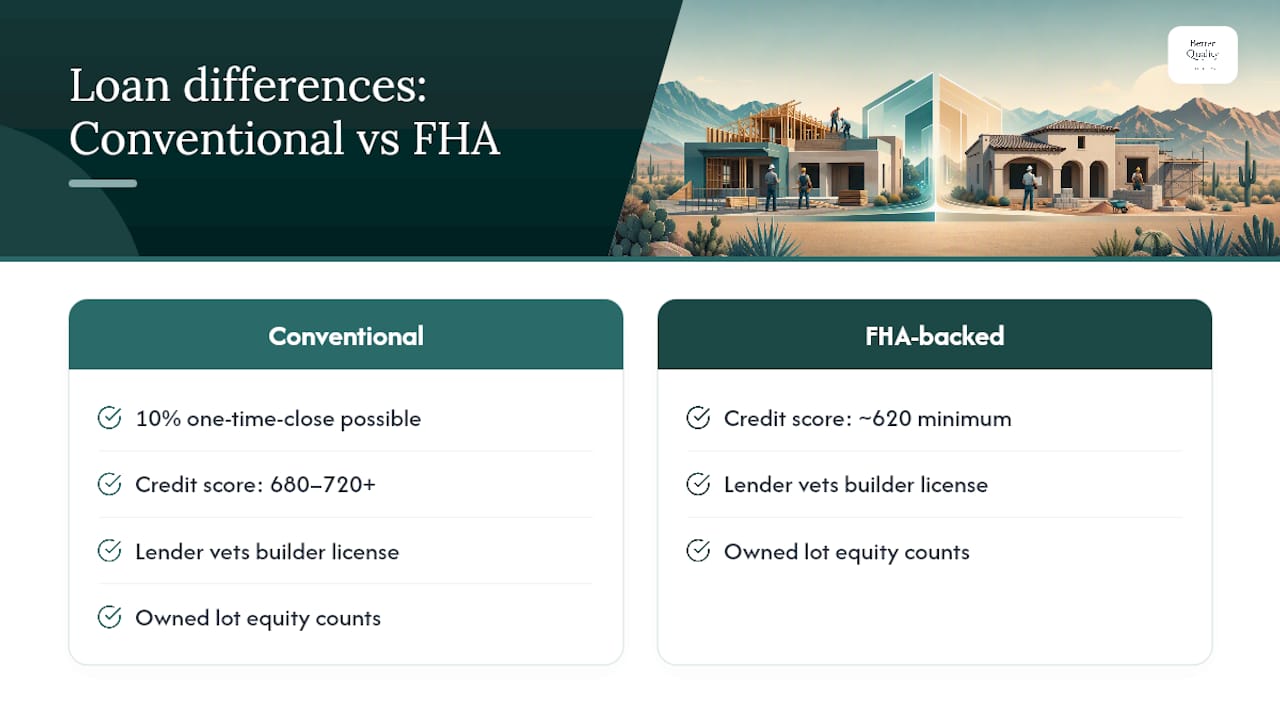
Why does my builder’s license matter to the lender? Lenders treat construction loans as higher risk and vet the builder’s Arizona Registrar of Contractors license, insurance, and experience before approving draws, since the builder’s performance directly affects the collateral being financed.
Sources
- Construction loans Arizona — District Lending
- Home Construction Loans in Arizona & AZ Home Builds | OneAZ Credit Union